Ministerial Decision No. 131 of 2026 - what is changing?
On 7 August 2026, the Ministry of Finance of the United Arab Emirates announced the extension of the Small Business Relief tax relief for CIT. Under Ministerial Decision No. 131 of 2026, the relief will apply to tax periods ending no later than 31 December 2029. The previous expiry date - the end of 2026 - has therefore been pushed back by three years.
This is important news for entrepreneurs doing business in the UAE, including Poles, who in recent years have increasingly been setting up companies in Dubai and other emirates. The extension gives small businesses more time to grow in a favourable tax environment before they become subject to the standard CIT rates.
It is worth stressing that the revenue threshold for the relief has not changed - it remains AED 3 million per year, in line with the earlier Ministerial Decision No. 73 of 2023. The relief applies to tax periods starting on or after 1 June 2023, which means the existing mechanism continues without a break.
What is Small Business Relief and who can benefit from it?
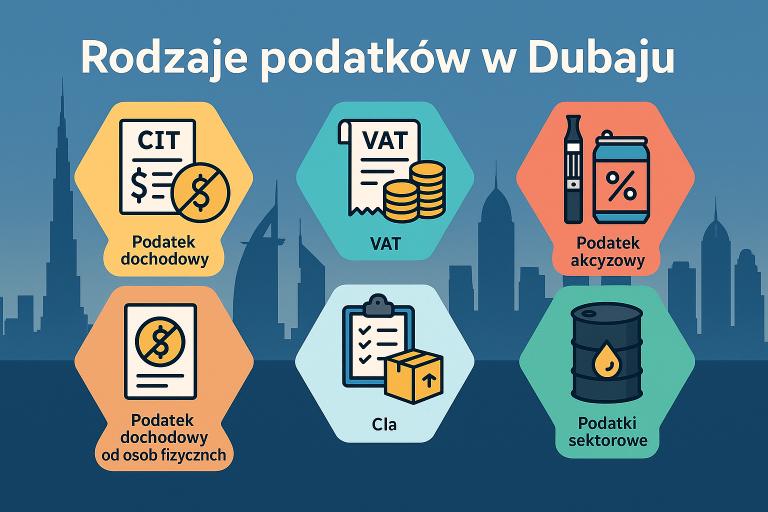
Small Business Relief is a relief within corporate income tax (Corporate Income Tax), which the UAE introduced relatively recently. Under it, businesses with annual revenue not exceeding AED 3 million can, as a rule, be exempted from paying CIT. It is a solution aimed at micro and small businesses that are only just building their position on the Emirati market.
The basic CIT rules in the UAE are as follows:
- 0% CIT - on income up to AED 375,000
- 9% CIT - on the portion exceeding AED 375,000
Small Business Relief allows businesses below the AED 3 million revenue threshold to avoid being subject to this rate, but the relief does not apply automatically. The business owner must actively elect it in the CIT tax return. This is a key point that many business owners forget - simply meeting the revenue criterion is not enough.
Even when using the relief, a company is required to:
- Register with the Federal Tax Authority (FTA) - the registration obligation applies to all entities subject to CIT.
- File tax returns - by the required deadline, indicating the election of the relief.
- Keep full accounting records - in line with Emirati requirements.
Who will not benefit from the relief? Important exclusions
The ministerial decision precisely defines which entities cannot benefit from Small Business Relief, even if their revenue does not exceed the AED 3 million threshold. The exclusions apply to two key categories of entities.
Qualifying Free Zone Persons
Entities with the status of Qualifying Free Zone Persons are not eligible for the relief. These companies benefit from a separate tax regime provided for free zones in the UAE, which has its own incentives - the legislator therefore considered that combining the benefits would be unjustified.
Companies belonging to multinational enterprise groups (MNEs)
The relief is also not available to companies that are part of multinational enterprise groups. This exclusion reflects the global trend of tightening tax systems against large multinational entities, consistent with, among others, OECD initiatives on minimum taxation.
Before relying on the relief, it is therefore worth carefully analysing whether the entity is subject to either of these exclusions. Incorrect application of Small Business Relief may result in having to pay additional tax together with interest and penalties from the FTA.
A company in Dubai and Polish tax obligations
For Polish entrepreneurs considering doing business in the UAE, it is crucial to understand that owning a company in the Emirates does not automatically remove Polish taxation. This is one of the most common mistakes made when planning international structures.
Poland, as the country of tax residence of most Polish entrepreneurs, taxes the worldwide income of its residents. In practice, this means that:
- Dividends paid by a UAE company are, as a rule, subject to tax in Poland at a rate of 19%.
- Controlled foreign company (CFC) rules may require the income of the Emirati company to be added to the Polish tax base, even if no dividend has been paid.
- The details of the structure matter - the legal form, the place of effective management, the type of activity carried out and the real economic substance in the UAE.
Each case requires an individual tax analysis taking into account both Emirati and Polish regulations. A poorly thought-out structure may not only fail to deliver savings, but may even expose the entrepreneur to additional burdens and the risk of a tax audit.
This is precisely why planning a business in the UAE is best entrusted to advisers who know both legal systems. Global Tax Partners specialises in the registration and legal and accounting support of companies in Dubai - both in free zones (Freezone) and on the local market (Mainland) - while helping to plan a structure that complies with Polish tax rules.
Summary of the changes and next steps
The extension of Small Business Relief until the end of 2029 is good news for small businesses in the UAE. The three-year extension of the relief gives entrepreneurs planning stability and time to scale their business. At the same time, the unchanged AED 3 million threshold and the formal obligations (registration, returns, records) are a reminder that the UAE tax system - although favourable - requires professional support.
For Polish tax residents, what remains key is setting up the structure correctly, taking into account both Emirati incentives and Polish obligations arising from CFC rules, dividend taxation and tax residence. Every situation is different and requires an individual approach.
If you are considering setting up a company in Dubai or want to check whether your current structure makes optimal use of the available reliefs - book a free consultation with the Global Tax Partners team. Our specialists will help you assess your situation and plan the next steps in line with the law of both jurisdictions. Call: +48 505 684 412 or write to us via the form on the website.
Have a question about this?
The first consultation is free - let us talk about your situation.